South America
From Chapter 10: South America
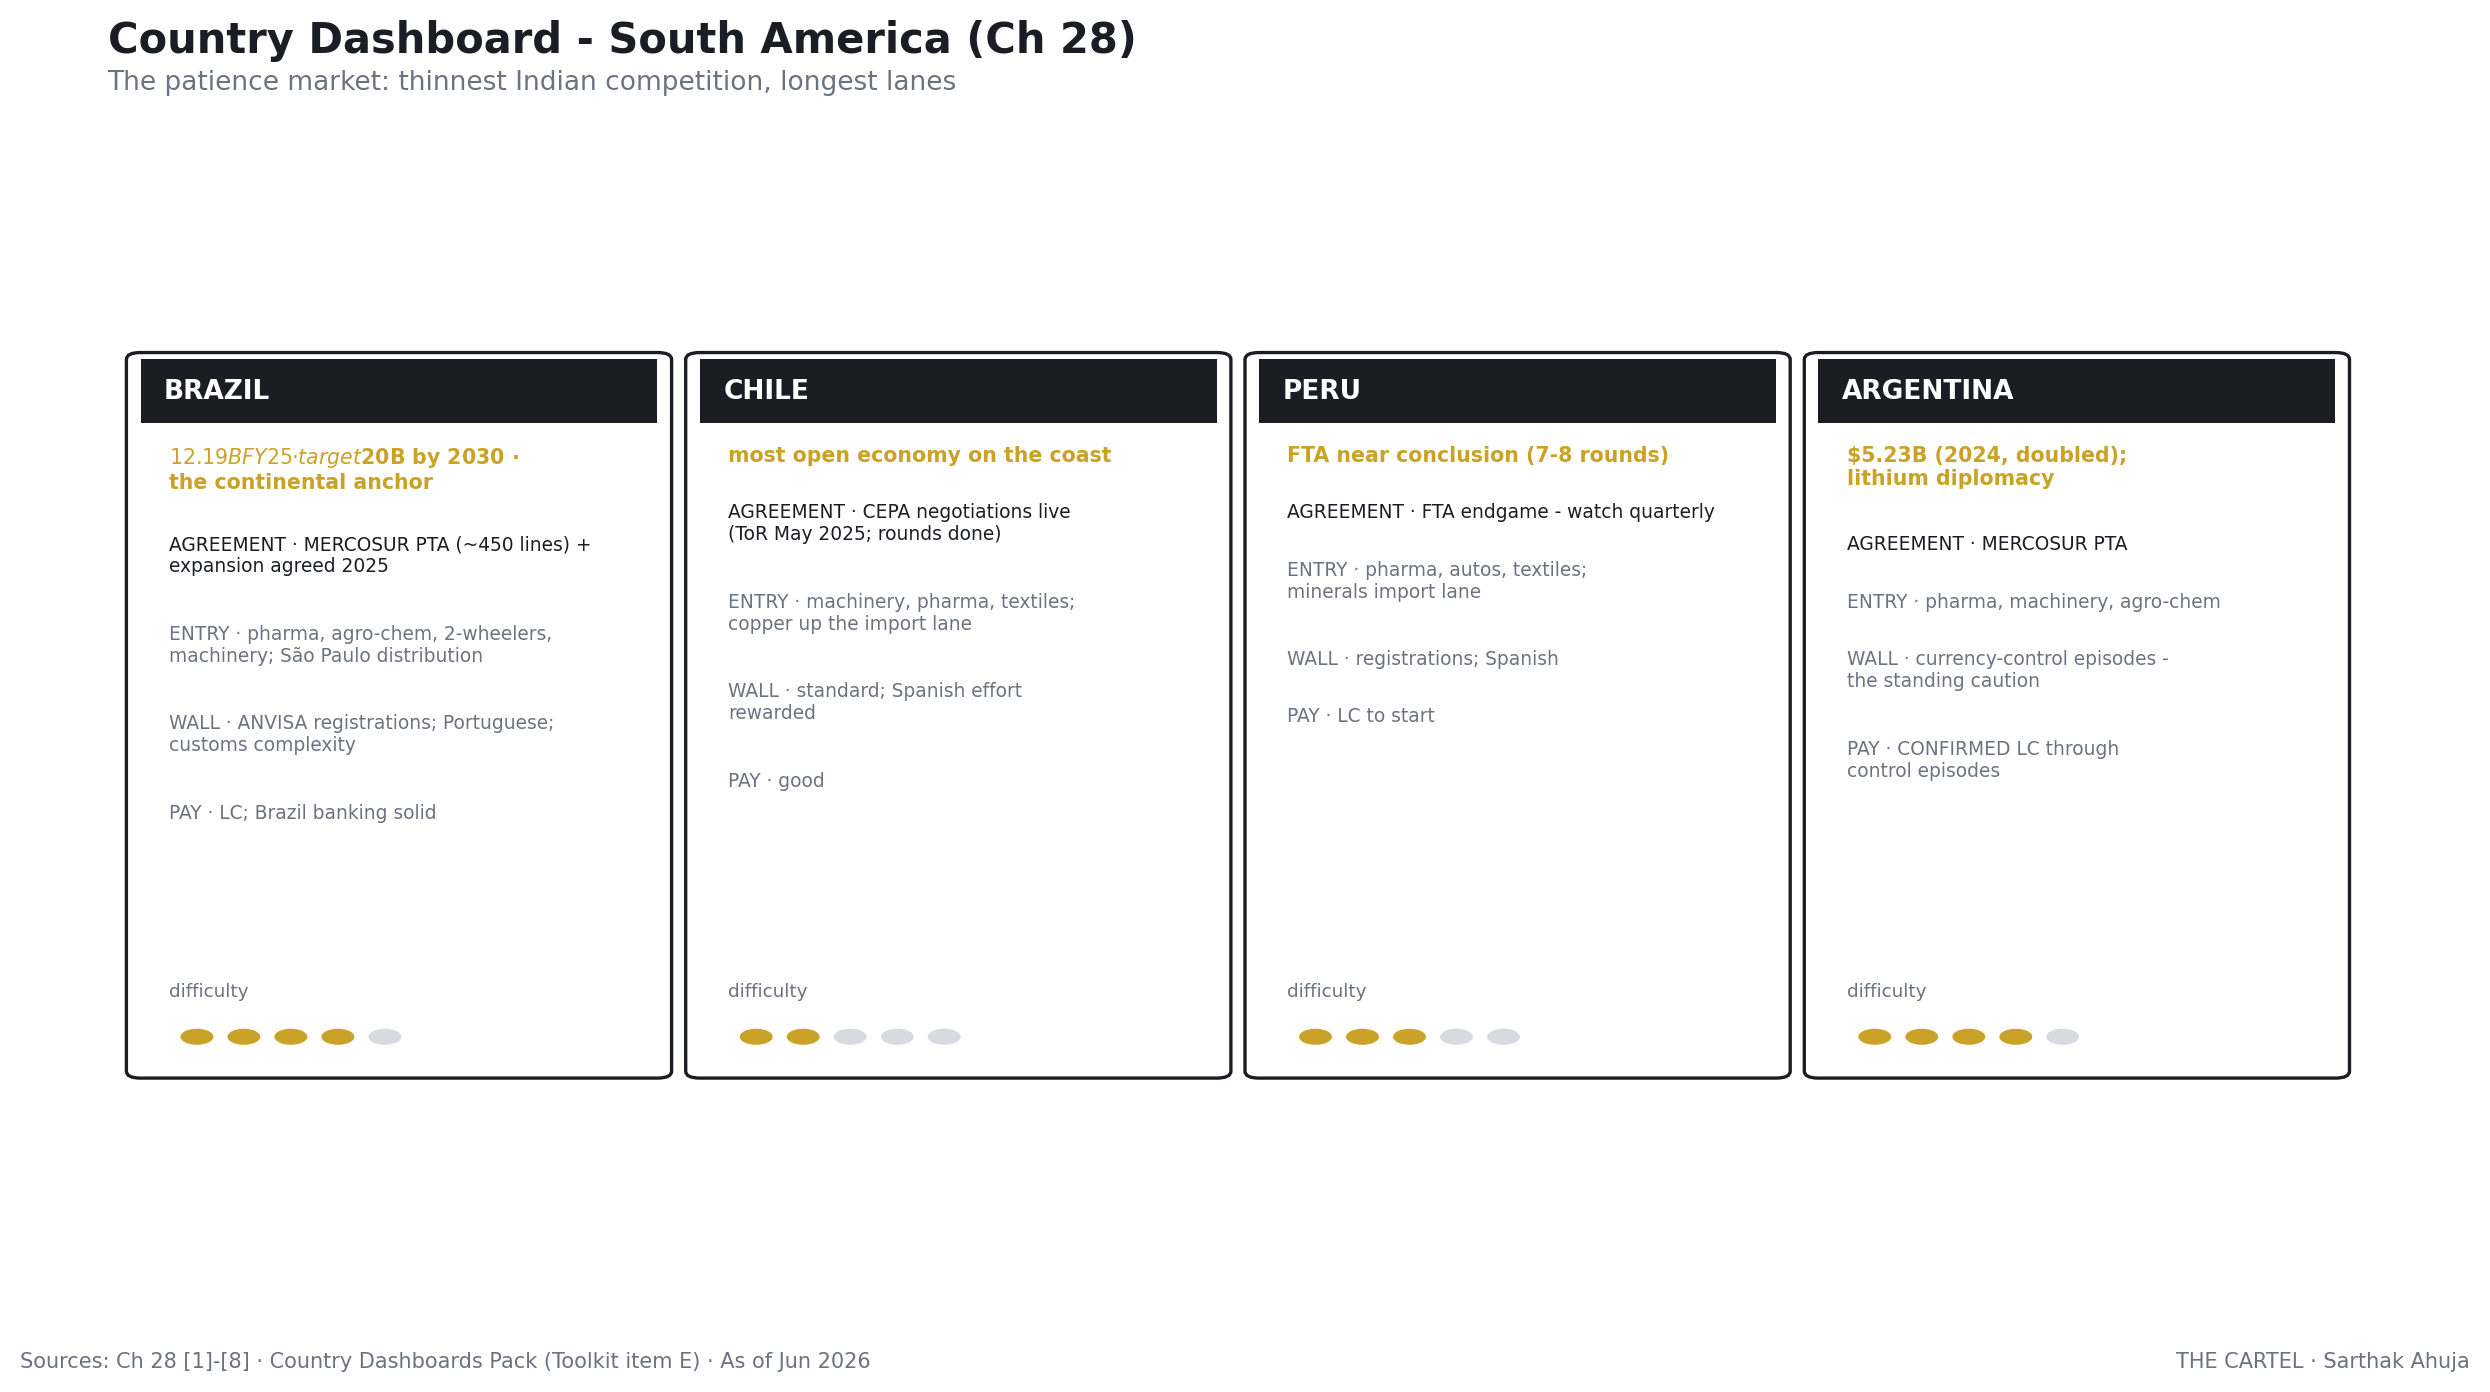
South America is the smallest, slowest and most distant market in this book, and that is its advantage. Few Indian exporters bother with it, so the ones who do tend to hold their accounts for decades. The costs are plain: long sailings, local testing, a second language and cautious credit terms. The reward is thin competition and margins that reflect it. Trade agreements are only now starting to move, which means the early work of finding an importer and building a shipping record will matter more than any tariff cut. This hub lists the position for Brazil, Chile, Peru and Argentina.
Key facts
- Brazil trade
- $12.19B in FY25; target $20B by 2030
- Brazil agreement
- MERCOSUR PTA (~450 lines); expansion agreed 2025
- Chile agreement
- CEPA negotiations live (terms of reference May 2025; rounds done)
- Peru agreement
- FTA: nine negotiation rounds completed as of late 2025; nearing conclusion
- Argentina trade
- $5.23B in 2024, growing a third
- Argentina payment
- letters of credit for new buyers; FX rationing is a standing hazard
As of October 2026
Dashboard